
Award Winning Trust Service
Advice On Trusts Service.
It’s free to speak with a expert in trusts anytime.
 Outstanding Client Engagement
- Excellent Client Loyalty
- Leaders in Mortgage Advice
- Leaders in Insurance Advice
The journey to
getting your trust sorted
Think of it as a relaxed chat to set you on the right path. You talk, we listen!
- Initial Meeting
- Instruction Appointment
- Draft Time
- Your Trust Is Done
Meet The Owners
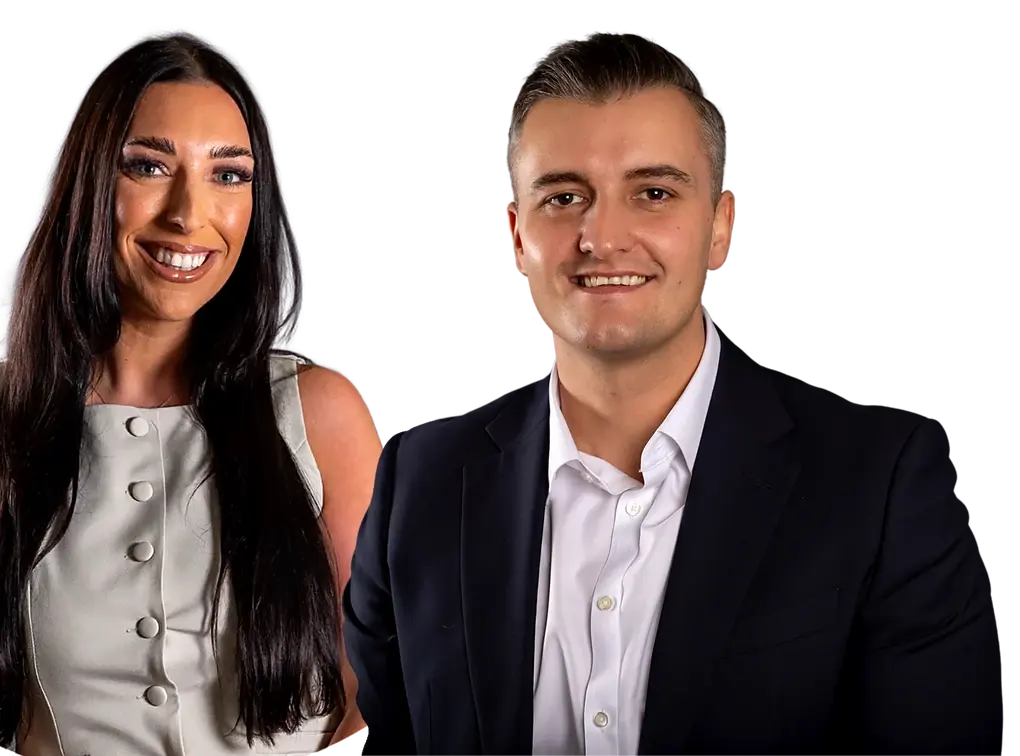
Simon & Kelly
“Going above and beyond is what we do; we LOVE our job, and most of all, we LOVE helping our clients.”
 Google Reviews
Quick Writing
Stop waiting weeks to get sorted.
Transparent Advice
Don't be left in the dark anymore.
The Journey To
Getting Your Trust Sorted
- 1
Initial Meeting
Book AppointmentLet’s grab a cuppa (or a Zoom). This is where we get to know you, your plans, and your goals. Think of it as a relaxed chat to set you on the right path. You talk, we listen!
- 2
Instruction Appointment
Get A Plan In PlaceWe’ll craft a personalised plan tailored to your needs, complete with all the suitable options.
- 3
Draft Time
Meet Your BrokerLeave the paperwork and all the heavy lifting to us. We will send you the draft ready for approval for you check first.
- 4
Your Trust Is Done
Let's Get StartedOnce everything is approved, the original documents are signed and are in place.
Why Use Protex Financial For
Getting a Trust??
Here at Protex Financial, we strive to make our only focus on you; this is why we can offer the leading range of advice for your families future.
Unfortunately, as many as one in three women and one in five men will require formal care at some point in their lives, with over 500,000 people currently residing in care homes. Under the Care Act 2014, if someone enters care, the Local Authority can use the value of their home to cover the cost of their care. As a result, this may leave little of their estate for their family once they pass away.
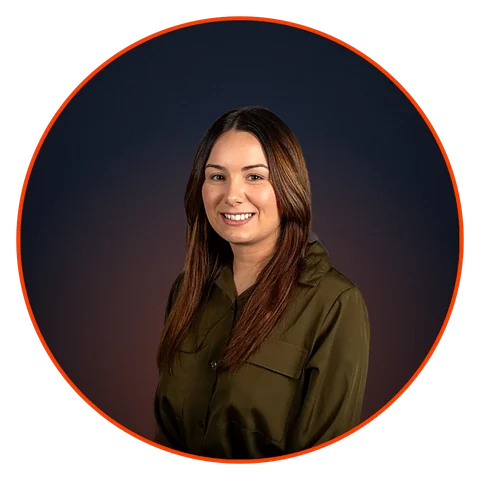
Meet Danielle
Danielle (LLB, LLM) is our trust and estate planning specialist at Protex Financial.
Driven by a passion for helping people secure their futures, Danielle founded her Wills & Estate Planning service to provide accessible and professional estate planning advice to those in need of professional guidance.
As a Professional Trust & Estate Planner, Danielle is dedicated to ensuring that individuals and families can confidently plan for the future. Danielle specialises in Wills, Trusts, Lasting Power of Attorneys, and various other aspects of estate planning, always focusing on delivering personalised solutions tailored to each client’s unique needs.
Simple Fees
Trust Advice Starting From
£510.00
For example, this package contains Will(s), severance of tenancy and life interest trust for the house
- Award-winning advisers
- Access to a wide range of experts
- Options to make changes in the future
- Enquire for a full and transparent price list
Trust & Estate Planning Services
A trust is a legal arrangement where your assets, such as money, property, or investments, are placed under the control of trustees for the benefit of specified beneficiaries. A trust can provide a flexible way to manage your assets both during your lifetime and after your death. They are commonly used in estate planning to protect assets, manage inheritance, and reduce tax liabilities.
Frequently Asked Questions
A trust is designed to manage and protect assets for the benefit of beneficiaries, according to the terms you set out. It allows you to control how and when your assets are distributed, ensuring your wealth is preserved and passed on in a structured way.
Anyone who wants to ensure their assets are managed carefully, either during their lifetime or after death, should consider a trust. Trusts are especially useful for individuals with young children, vulnerable beneficiaries, or significant estates that might be subject to inheritance tax.
Assets placed in certain types of trusts can be excluded from your estate for inheritance tax purposes. This can help reduce the overall tax burden on your estate, allowing more of your wealth to be passed on to your beneficiaries rather than being paid in tax.
If you remarry after the death of a spouse and fail to update your will, your estate may be at risk of “sideways disinheritance.” This occurs when the estate you and your former spouse built together passes to your new spouse’s family, potentially bypassing your own children entirely.
This can happen because marriage automatically revokes any previous wills. If you don’t update your will, it becomes invalid, and your estate will be distributed according to the rules of intestacy, which may not align with your wishes.
To prevent this, you can set up a Property Protection Trust or a Flexible Life Interest Trust. These trusts ensure that your chosen beneficiaries, such as your children, will still inherit your estate even after you remarry.
As of 2024, Inheritance tax (IHT) is a tax applied to the total value of everything you own when you pass away. The current threshold, known as the Nil Rate Band, is £325,000. Any amount above this threshold is subject to a 40% tax. For example, if your estate is valued at £425,000, the taxable portion would be £100,000, resulting in a tax bill of £40,000, which reduces the amount available to your loved ones.
For married couples, the IHT threshold is £650,000 for the current tax year, provided that the first to pass leaves their entire estate to the surviving spouse. This allows the surviving spouse to benefit from both partners’ Nil Rate Bands.
However, this system doesn’t benefit everyone. Unmarried couples do not enjoy the same tax reliefs, and it may not be suitable for those who do not wish to leave everything to their spouse.
If you are unmarried, you could consider including a Nil Rate Band Discretionary Trust in your will. This would allow your partner to take advantage of your £325,000 allowance, helping to reduce the IHT burden on your estate and preserve more of your assets for your loved ones.
A discretionary trust gives trustees the flexibility to decide how, when, and to whom to distribute the trust’s assets. This can be useful if your beneficiaries have different needs or if you want to allow trustees to manage the assets based on current circumstances.
Yes, certain types of trusts, such as a Property Protection Trust, can protect your home from being used to pay for long-term care fees. By placing your home in trust, you can ensure it passes to your beneficiaries while still providing for your care needs.
Yes, you can establish a trust within your will, known as a will trust. This type of trust comes into effect after your death and allows you to dictate how your assets are managed and distributed, offering greater control and protection for your beneficiaries.
A life interest trust allows a named beneficiary to receive income from the trust (such as rent or dividends) during their lifetime. Still, the capital (the property or investments) is preserved and passed on to other beneficiaries, often children, after the life tenant’s death.
There are typically three key parties involved in a trust:
- The settlor: The person who creates the trust and transfers assets into it.
- Trustees: Individuals or companies appointed to manage the trust and distribute assets according to its terms.
- Beneficiaries: The people or organisations who benefit from the trust’s assets.
A trust is focused on managing assets to benefit beneficiaries, either during your lifetime or after death. An LPA, on the other hand, is a legal document that allows someone you trust to make decisions on your behalf if you lose mental capacity, covering financial and health-related matters.
Some trusts are flexible and can be amended or cancelled (revoked) by the settlor, while others, known as irrevocable trusts, cannot be changed once they are established. It’s important to choose the right type of trust based on your specific needs and intentions.