
Award Winning Insurance Broker
Share Holder Protection.
It’s free to speak with an insurance broker anytime.
 Outstanding Client Engagement
- Excellent Client Loyalty
- Leaders in Mortgage Advice
- Leaders in Insurance Advice
The journey to
protecting what matters most
Think of it as a relaxed chat to set you on the right path to financial security. You talk, we listen!
- Initial Meeting
- Personalised Advice
- We Take Care of the Rest
- You Are Covered
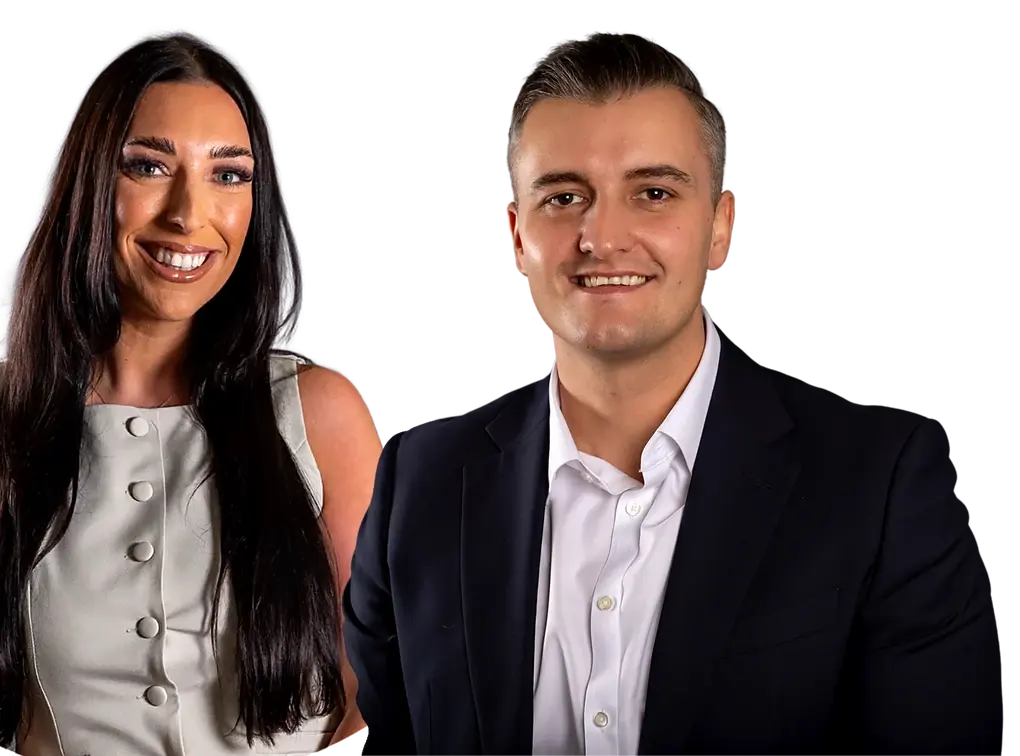
Meet The Owners
Simon & Kelly
“Going above and beyond is what we do; we LOVE our job, and most of all, we LOVE helping our clients.”
 Google Reviews
Quick Decisions
Stop waiting weeks to get a decision.
Transparent Advice
Don't be left in the dark anymore.
We Can Search Thousands Of
Shareholder Protection Deals
The Journey to
Protecting What Matters Most
- 1
Initial Meeting
Book AppointmentLet’s grab a coffee (or a Zoom). This is where we get to know you, your concerns, and your protection goals. Think of it as a relaxed chat to set you on the right path to financial security. You talk, we listen!
- 2
Personalised Advice
Get Personalised PlanWe’ll craft an insurance plan tailored to your needs, complete with all the suitable options. We’re like your personal insurance matchmaker, finding the best deal to make protecting what matter most easy.
- 3
We Take Care of the Rest
Meet Your BrokerLeave the paperwork, provider chasing, and all the heavy lifting to us. All you need to do is sit back and relax while we make it happen behind the scenes. Our award-winning insurance team is available 7-days a week.
- 4
You Are Covered
Let's Get StartedYour new insurance is set up, and it’s time to pop the bubbly! Like all our 5-star customers, you are now financially protected should the worst happen.
Different Types of
Shareholder Protection
To provide a lump sum to buy out the deceased shareholder’s shares.
- Term Life Insurance: Covers shareholders for a specific period. If a shareholder dies during the term, the policy pays out a lump sum to purchase their shares.
- Whole Life Insurance: Provides permanent coverage, paying out whenever the shareholder dies, ensuring funds are always available for share purchase.
Why Use Protex Financial For
Shareholder Protection?
Here at Protex Financial, we strive to focus only on you; this is why we can offer the best range of Shareholder Protection advice with access to thousands of products the insurance market offers. Our Shareholder Protection brokers can search thousands of products to ensure you are getting the most suitable deal you can possibly get.
The FCA, the Financial Conduct Authority, regulates our team at Protex Financial. This means everything we do is for you; we must offer you the leading and most suitable Shareholder Protectionn options, rates, and business Insurance advice.
Frequently Asked Questions
Losing a valuable shareholder, whether through illness or death, can harm a business. Here are some advantages of taking out Shareholder Protection to safeguard your business.
Staying in control of the business prevents the shareholding from being inherited by an unwanted beneficiary whose priorities may not align with the business.
It can ensure greater transparency for the insured person’s beneficiaries as they’ll have a clearer picture of what they will receive for selling the shares to other shareholders.
You can avoid costly buy-out funds (taking on debt) and won’t have to fall into your savings.
By making an eventual share transfer as orderly as possible, you can reduce disruption at a challenging time for your business.
One way to determine how much shareholder protection you require is to estimate the amount of capital the remaining shareholder partners would need to generate to buy a shareholding in the business.
Losing a shareholder/business partner could substantially impact your business, their families and livelihood. It not only puts financial strain on the business but can also influence who will continue to run the business, especially if the remaining shareholders cannot raise the necessary funds to buy out the deceased shareholders’ beneficiaries.
If your business is structured in such a way with shareholders & business partners, it’s essential to think about what would happen if the worst was to happen to them. Would your business have the required funds to purchase the deceased share? And if not, how the would company then restructure? Would you have to get a loan? Or maybe even be forced to sell the entire company?
If a business owner dies or is diagnosed with a critical illness*, share protection can provide a lump sum to the remaining business owners.
This means that if a valid claim is made during the policy’s duration, the lump sum could be used to help purchase the deceased partner, shareholding director, or member’s interest in the business.
If a business owner dies with no shareholder’s protection in place, their share in the business may be passed onto their family. This means that the surviving business owners could lose control of a proportion of the business, or in some circumstances, all of it. The family may choose to become involved in the ongoing running of the business or could even sell their share to a competitor to get their compensation for the deceased share.
Our team of experts here at Protex Financial recommend you start looking for Shareholders Protection as soon as you are able to point out that the loss of a shareholder can create such a financial impact on the business.
There are several types, including:
- Life Insurance: Provides funds to buy out shares if a shareholder dies.
- Critical Illness Insurance: Covers the cost of buying shares if a shareholder is diagnosed with a critical illness.
- Combined Life and Critical Illness Insurance: Offers comprehensive coverage for both death and critical illness.
- Cross-Option Agreement: Ensures a structured process for share transfer between shareholders.
- Buy and Sell Agreement: Establishes pre-agreed terms for buying and selling shares.
- Single Option Agreement: Provides flexibility in the transfer of shares.
- Business Loan Protection: Protects against financial instability due to loans guaranteed by shareholders.
- Key Person Insurance: Covers the loss of a key shareholder vital to the business’s success.
- Partnership Protection: Specifically for partnerships, ensuring smooth transition and continuity.
Shareholder Protection works by providing a lump sum payout to the business or remaining shareholders if a covered event occurs, such as the death or critical illness of a shareholder. This payout can be used to buy the affected shareholder’s shares, ensuring that control of the company remains within the agreed group and preventing outside parties from gaining influence.
The coverage amount is typically based on the value of the shares held by each shareholder. It’s important to regularly review and update this valuation to reflect changes in the company’s worth and ensure that the coverage remains adequate. Consulting with a financial advisor or insurance specialist can help determine the appropriate coverage amount.
The tax treatment of premiums can vary depending on the jurisdiction and specific circumstances. In some cases, premiums may be considered a business expense and thus tax-deductible. However, if the policy benefits the business directly, the premiums might not be deductible. Consulting with a tax advisor or accountant is recommended for specific guidance.
If a shareholder wants to leave voluntarily, the process for selling their shares should be outlined in the company’s buy-sell agreement or shareholders’ agreement. Shareholder Protection typically covers involuntary departures due to death or critical illness, but having clear agreements in place for voluntary departures is also essential for smooth transitions.
Yes, Shareholder Protection can be arranged to cover multiple shareholders, ensuring that the business is protected against the loss of any key individuals. Each shareholder can have a separate policy tailored to their shareholding value and specific needs.
The duration of Shareholder Protection coverage depends on the terms of the policy. Typically, it is aligned with the term of the life or critical illness insurance policies, which can vary from a specific number of years (term insurance) to the lifetime of the shareholder (whole life insurance). The coverage should be reviewed regularly to ensure it continues to meet the needs of the business and its shareholders.