
Award Winning Mortgage Advice
Expert Remortgage Advice.
It’s free to speak with a mortgage adviser anytime.
 Outstanding Client Engagement
- Excellent Client Loyalty
- Leaders in Mortgage Advice
- Leaders in Insurance Advice
The journey to your
new mortgage!
Think of it as a relaxed chat to set you on the right path. You talk, we listen!
- Initial Meeting
- Personalised Advice
- We Take Care of the Rest
- Collect Your Keys
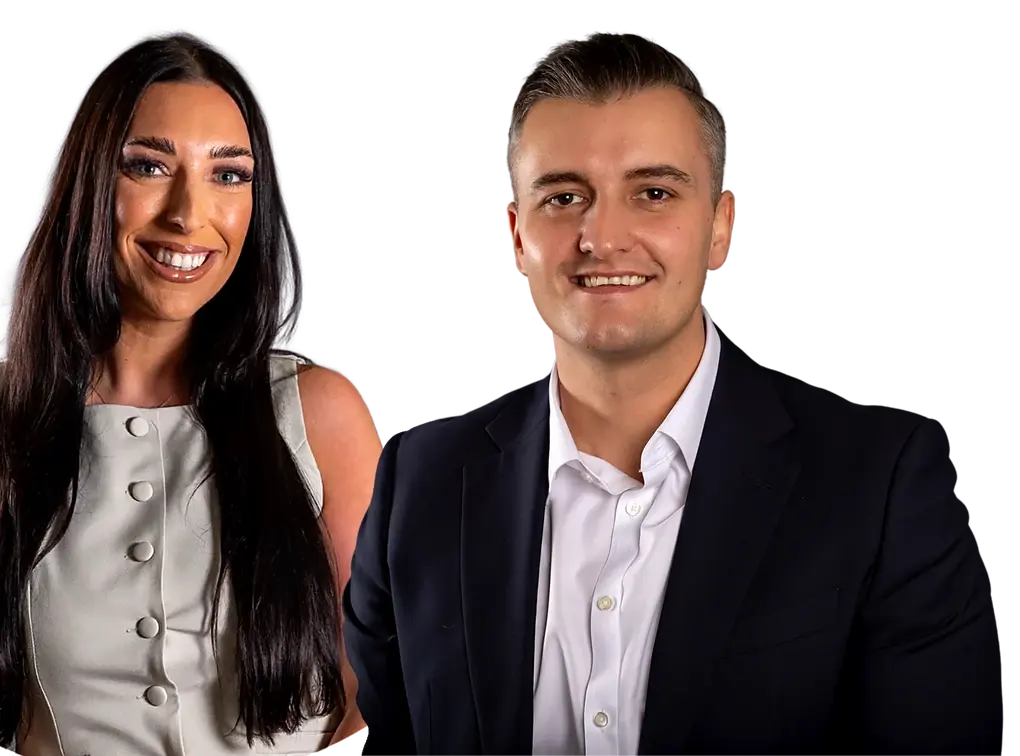
Meet The Owners
Simon & Kelly
“Going above and beyond is what we do; we LOVE our job, and most of all, we LOVE helping our clients.”
 Google Reviews
Quick Decisions
Stop waiting weeks to get a decision.
Transparent Advice
Don't be left in the dark anymore.
We Can Search Thousands Of
Mortgage Deals
Latest Mortgage Deals
The Journey To Your
New Mortgage!
- 1
Initial Meeting
Request an AppointmentLet’s grab a coffee (or a Zoom/call). This is where we get to know you, your plans, and your goals. Think of it as a relaxed chat to set you on the right path. You talk, we listen!
- 2
Personalised Advice
Check my eligibilityWe’ll craft a mortgage plan tailored to your needs, complete with all the suitable options. We’re like your personal mortgage matchmaker, finding the most suitable deal to make your dream become a reality!
- 3
We Take Care of the Rest
Meet Your BrokerLeave the paperwork, lender chasing, and all the heavy lifting to us. All you need to do is sit back and relax while we make it happen behind the scenes. Our award-winning team is available 7-days a week.
- 4
Collect Your Keys
Let's Get StartedYour mortgage offer is in, and it’s time to pop the bubbly! Like all our 5-star customers, you are now one step closer to making your goals a reality.
Why Use Protex Financial For A
Remortgage?
Here at Protex Financial, we strive to make our only focus on you; this is why we can offer the best range of Mortgage Advice with access to 1000’s of remortgage products that the market has to offer. Our mortgage brokers are able to search thousands of products to make sure you are getting the most suitable deal you can possibly get.
Our mortgage team here at Protex Financial are regulated by the FCA, the Financial Conduct Authority. This means everything we do is for you; we are obligated to offer you great rates, great deals and great remortgage advice.
Simple Fees
Transparent, simple and straightforward. You only pay our fee once we get you pre-approved and a mortgage in principle.
Remortgage
£0to£176
Moving to a new deal when your current one ends. Depending on your case, it can cost nothing at all.
Standard case
£376
A straightforward purchase, whether you are buying your first home or moving to your next one.
Complex case
£476
Cases that need more work, such as adverse credit, buy to let, self-employed income, visa applications or when you need to transfer some equity.
Ltd company transactions
£576
Buying or remortgaging a property through a limited company, such as a buy to let held by your company.
- Access to whole of market
- Award-winning advisers
- Access to a wide range of expert solicitors
- Mortgage protection built to last
Remortgaging Tips
Before you can think about taking out another mortgage, you need to know your present deal inside out. This means familiarising yourself with things like rates of interest and monthly repayments, as well as how much is left outstanding on the loan.
Also, check for any early redemption charges or exit fees. Once armed with these facts, it becomes possible to judge whether switching lenders could save cash or secure more favourable terms. Please bear in mind that the amount of equity held in a property may affect the rates and products available. So, if nothing else, make sure you’re fully aware of what’s going on with your current mortgage; it’s the first step towards making an informed decision!
Mortgage Calculator
Remortgaging
Frequently Asked Questions
A remortgage involves taking out a new mortgage on the same property. Many homeowners lock into a new deal for typically 2, 3, or 5 years to ensure peace of mind.
If you have substantial equity in your home, a remortgage application may allow you to borrow additional funds. These funds can be used for various purposes, such as repaying debts or financing home improvements.
You’ll also have the option to adjust the mortgage term, either shortening or extending it to modify the monthly payments. Generally, a shorter mortgage term means you’ll pay less interest over the life of the mortgage.
Your mortgage broker can discuss these options with you and answer any questions.
If you are over 50, alternative products to traditional mortgages are available. These include retirement interest-only mortgages or lifetime mortgages, such as equity release mortgages, which may better suit your situation.
Yes, this process is known as a product transfer. As remortgage experts, we always compare your current lender’s offer with other lenders’ available offers. This comprehensive comparison is a key part of our remortgage service!
Often, lenders make it very easy for borrowers to secure a new fixed-rate deal via mobile apps or internet banking portals without first providing mortgage advice.
Without a mortgage broker, you might make costly mistakes by fixing again without fully considering all your options.
If you receive a new deal offer, consult a mortgage advisor first. We can review your lender’s offer and compare it to other options to ensure you make the best decision.
Yes, it’s possible. We offer remortgage advice for those with bad credit. Many clients are surprised to learn that bad credit remortgages are quite common. Generally, the more equity you have in your home, the better your chances of approval.
Bad credit options include securing a mortgage despite having a CCJ, defaults, missed payments, or payment plans.
If you’re considering using your mortgage to repay debts, this could be a viable option for you as well. Your mortgage broker will discuss both the pros and cons of this approach, as debt consolidation remortgages are considered specialist lending.
Yes, you can remortgage to repay debts. Typically, a debt consolidation remortgage involves repaying outstanding credit card or personal loan balances by adding them to your mortgage.
However, this approach is not without risk. We’ll help you weigh the pros and cons of a debt consolidation remortgage and recommend the best course of action.
If you’re not locked into a fixed-rate deal or if your property is currently mortgage-free, you can remortgage at any time.
If you have a fixed-rate mortgage, it’s a good idea to schedule a free remortgage consultation about 6-months before your deal ends to explore your options.
If you need to remortgage in the middle of a fixed-rate deal, you can still do so, but early redemption fees may apply.
In such cases, our mortgage broker team will compare alternatives, such as a second-charge mortgage (also known as a secured loan) or a further advance mortgage from your existing lender, to find the most cost-effective solution.
Remortgaging can offer numerous benefits depending on your financial situation and goals. Here are some compelling reasons to consider remortgaging:
1. Secure a Lower Interest Rate
One of the most common reasons to remortgage is to take advantage of lower interest rates. By switching to a lower rate, you can reduce your monthly payments and save money over the life of the loan.
2. Release Equity
If your property has increased in value since you took out your original mortgage, remortgage can allow you to release some of that equity. You can use this extra cash for home improvements, debt repayment, or other financial needs.
3. Switch to a More Suitable Mortgage Product
Your financial situation or goals may have changed since you took out your original mortgage. Remortgaging allows you to switch to a different type of mortgage product that better suits your current needs, such as moving from a variable to a fixed rate for more payment stability.
4. Consolidate Debts
If you have high-interest debts such as credit cards or personal loans, consolidating them into your mortgage can be a more manageable and cost-effective way to pay them off. This is often referred to as a debt consolidation remortgage.
5. Overpay and Reduce Debt Faster
Some mortgages come with restrictions on overpayments. By remortgaging, you might find a deal that allows you to make larger or more frequent overpayments, helping you pay off your mortgage faster and reduce the interest you pay overall.
6. Improve Your Financial Flexibility
Remortgaging can also provide more flexible terms, such as taking payment holidays or switching to a mortgage with lower early repayment charges. This flexibility can be beneficial if your financial situation changes unexpectedly.
7. Avoid Reversion Rates
When your current mortgage deal ends, you may be moved onto your lender’s Standard Variable Rate (SVR), which is often higher than the rate on your initial deal. Remortgaging before this happens can help you avoid these higher rates and keep your payments lower.
Before deciding, it’s essential to weigh the potential costs and benefits of remortgaging. Consulting with a mortgage advisor can help you understand your options and make an informed decision tailored to your financial circumstances.
A trusted and experienced mortgage broker can help you compare deals and identify the most suitable options as you approach the end of your initial mortgage term. They will consider your financial goals, current circumstances, and future plans to recommend the best mortgage products available.
During your free, no-obligation mortgage consultation, we will address all your questions and provide a clear understanding of your options. We will explain each option’s potential benefits and drawbacks, helping you make an informed decision. We aim to ensure you find a mortgage solution that meets your needs and helps you achieve financial stability and peace of mind.
Whether you’re looking to secure a better interest rate, release equity, or explore alternative mortgage products, our expert guidance will support you every step of the way.
Remortgaging refers to taking out a new mortgage on a property you own, either to replace your existing mortgage or borrow additional funds against your property’s equity. Here’s a more detailed explanation of what remortgaging involves:
Replacing Your Existing Mortgage
When you remortgage, you switch your current mortgage to a new deal, usually with a different lender, although sometimes with the same lender. The main reasons for doing this include securing a lower interest rate, obtaining better terms, or moving to a mortgage product that better suits your current financial situation and goals.
Borrowing Additional Funds
Remortgaging can also involve borrowing extra money from your existing mortgage balance. This is often done to release equity, which is the difference between the current value of your property and the outstanding mortgage balance. The additional funds can be used for various purposes, such as home improvements, consolidating other debts, or financing large purchases.
Reasons to Remortgage
- Lower Interest Rates: To reduce your monthly payments and overall interest costs.
- Better Mortgage Terms: Find a mortgage product offering more favourable terms or greater flexibility.
- Debt Consolidation: To combine high-interest debts into your mortgage for easier management and potentially lower overall interest.
- Equity Release: To access the increased value of your property for personal use.
The Process of Remortgaging
- Assessment: Review your current mortgage, financial situation, and goals.
- Comparison: Compare deals from various lenders to find the best option.
- Application: Apply for the new mortgage, providing the necessary documentation and information.
- Valuation: The new lender will conduct a property valuation to determine its market value.
- Approval: Once approved, your new lender will pay off your existing mortgage and set up the new one.
Key Considerations
- Fees and Costs: Remortgaging can involve costs such as arrangement fees, valuation fees, and legal fees. Ensure these costs are outweighed by the benefits.
- Timing: Consider the best time to remortgage, especially if you’re currently on a fixed-rate deal with early repayment charges.
- Advice: Consulting with a mortgage broker can provide valuable insights and help you navigate the remortgage process efficiently.
Remortgaging can be a smart financial move if done for the right reasons and with careful consideration of all associated costs and benefits.
The process of remortgaging typically takes between 4 to 8 weeks, but this timeline can vary depending on several factors. Here’s a breakdown of the stages involved and what can influence the duration:
Initial Consultation and Application (1-2 weeks)
- Consultation: Meeting with a mortgage broker or lender to discuss your needs and options. This can take a few days to a week.
- Application: Submitting your application along with required documents such as proof of income, identification, and details of your current mortgage.
Valuation and Offer (2-3 weeks)
- Valuation: The new lender will arrange a valuation of your property to determine its current market value. This can take a week or two, depending on the availability of surveyors.
- Underwriting: The lender reviews your application and conducts credit checks. This underwriting process can take another week or two.
Legal Work and Completion (2-3 weeks)
- Solicitor Involvement: A solicitor or conveyancer will handle the legal aspects of the remortgage. This includes checking the title deeds and coordinating with your current lender to pay off the existing mortgage.
- Final Checks: The lender conducts final checks and prepares the mortgage offer.
- Completion: Once all checks are complete and the offer is accepted, the new mortgage is set up, and the old mortgage is paid off.
Factors That Can Affect the Timeline
- Document Readiness: Having all your documents ready and complete can speed up the application process.
- Property Valuation Delays: Availability of surveyors and the time taken to conduct the property valuation can impact the timeline.
- Lender Efficiency: Different lenders have varying processing times. Some are quicker at handling applications and underwriting.
- Legal Work: The efficiency of your solicitor or conveyancer can also influence the duration of the remortgaging process.
- Complex Cases: If your financial situation is complex or if there are issues with the property’s title, the process might take longer.
Tips to Speed Up the Process
- Prepare Documents Early: Gather all necessary documentation before starting the application.
- Choose an Efficient Lender: Research lenders known for their quick processing times.
- Stay in Communication: Regularly follow up with your broker, lender, and solicitor to ensure everything is on track.
- Clear Debts: Resolve any outstanding issues that might complicate your application, such as unpaid debts or credit issues.
When applying for a mortgage, having the right documents ready can help streamline the process. Here’s a list of the key documents you’ll typically need:
-
Proof of Identity:
-
Passport or Driving Licence
-
Proof of Address:
-
Recent Utility Bill (within the last 3 months)
-
Council Tax Bill
-
Proof of Income:
-
For Employed Applicants:
-
Last 3 months’ Payslips
-
For Self-Employed Applicants:
-
At least 1 years’ Tax calculations and overviews
-
At least 1-years Full accounts (if LTD company)
-
Bank Statements:
-
Latest 3 months’ Bank Statements
-
Proof of Deposit:
-
Savings Account Statements
-
Evidence of Gifted Deposits (if applicable)
-
Credit Report:
-
A copy of your Credit Report (check now – credit report)
Having these documents ready will help your mortgage broker or lender process your application more efficiently. If you have any specific circumstances or need further assistance, our team at Protex Financial is here to guide you through every step of the mortgage process.
When your current mortgage deal ends, you have two primary options: remortgage or a product transfer.
Remortgage
Definition: Remortgaging involves switching your existing mortgage to a new one, either with your current lender or a different lender. This often includes paying off your current mortgage and taking out a new mortgage with new terms and conditions.
Product Transfer
Definition: A product transfer involves switching to a new mortgage deal with your current lender. You retain the same mortgage balance and lender, but you move to a different mortgage product offered by your existing lender.