
Award Winning Mortgage Advice
Shared Ownership Mortgage Advice.
It’s free to speak with a mortgage adviser anytime.
 Outstanding Client Engagement
- Excellent Client Loyalty
- Leaders in Mortgage Advice
- Leaders in Insurance Advice
The journey to your
new mortgage!
Think of it as a relaxed chat to set you on the right path. You talk, we listen!
- Initial Meeting
- Personalised Advice
- We Take Care of the Rest
- Collect Your Keys
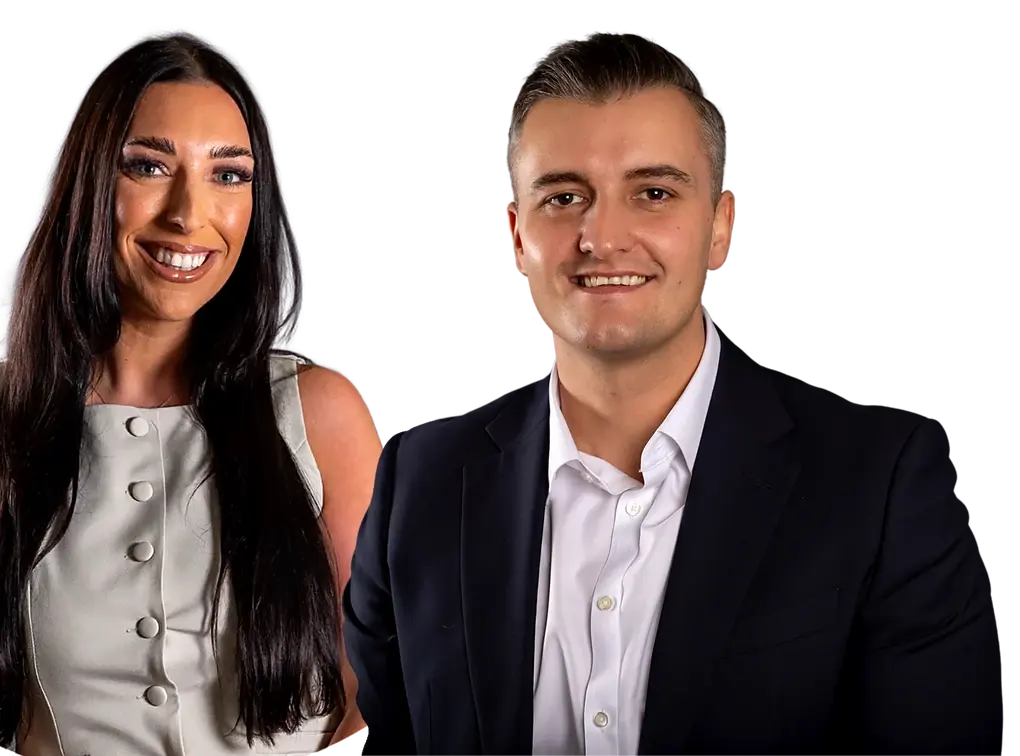
Meet The Owners
Simon & Kelly
“Going above and beyond is what we do; we LOVE our job, and most of all, we LOVE helping our clients.”
 Google Reviews
Quick Decisions
Stop waiting weeks to get a decision.
Transparent Advice
Don't be left in the dark anymore.
We Can Search Thousands Of
Mortgage Deals
Latest Mortgage Deals
The Journey To Your
New Mortgage!
- 1
Initial Meeting
Request an AppointmentLet’s grab a coffee (or a Zoom/call). This is where we get to know you, your plans, and your goals. Think of it as a relaxed chat to set you on the right path. You talk, we listen!
- 2
Personalised Advice
Check my eligibilityWe’ll craft a mortgage plan tailored to your needs, complete with all the suitable options. We’re like your personal mortgage matchmaker, finding the most suitable deal to make your dream become a reality!
- 3
We Take Care of the Rest
Meet Your BrokerLeave the paperwork, lender chasing, and all the heavy lifting to us. All you need to do is sit back and relax while we make it happen behind the scenes. Our award-winning team is available 7-days a week.
- 4
Collect Your Keys
Let's Get StartedYour mortgage offer is in, and it’s time to pop the bubbly! Like all our 5-star customers, you are now one step closer to making your goals a reality.
Why Use Protex Financial For
Shared Ownership Applications?
Here at Protex Financial, we strive to make our only focus on you; this is why we can offer the best range of Mortgage Advice with access to 1000’s of shared ownership mortgage products that the market has to offer. Our mortgage brokers are able to search thousands of products to make sure you are getting the most suitable deal you can possibly get.
Our mortgage team here at Protex Financial are regulated by the FCA, the Financial Conduct Authority. This means everything we do is for you; we are obligated to offer you great rates, great deals and great shared ownership mortgage advice.
Simple Fees
Transparent, simple and straightforward. You only pay our fee once we get you pre-approved and a mortgage in principle.
Remortgage
£0to£176
Moving to a new deal when your current one ends. Depending on your case, it can cost nothing at all.
Standard case
£376
A straightforward purchase, whether you are buying your first home or moving to your next one.
Complex case
£476
Cases that need more work, such as adverse credit, buy to let, self-employed income, visa applications or when you need to transfer some equity.
Ltd company transactions
£576
Buying or remortgaging a property through a limited company, such as a buy to let held by your company.
- Access to whole of market
- Award-winning advisers
- Access to a wide range of expert solicitors
- Mortgage protection built to last
Shared Ownership Tips
Shared ownership allows you to buy a share of a property and pay rent on the remaining share. This can make homeownership more affordable.
Steps:
- Initial Share: Typically, you can buy between 25% and 75% of the property.
- Rent Payments: You’ll pay rent on the share you don’t own, usually at a reduced rate.
Mortgage Calculator
Shared Ownership
Frequently Asked Questions
A shared ownership mortgage is a bank loan that enables you to buy a portion of a property while renting the remainder.
The property must be listed for sale under the shared ownership scheme.
Typically, a shared ownership mortgage allows you to buy between 25% and 75% of the property, although some homes allow you to purchase as little as 10%. You will then pay rent on the remaining share.
You will need a 5% deposit for your mortgage, calculated based on the share you are buying, not the total property value.
Obtaining a shared ownership mortgage can be more challenging than a regular mortgage due to the additional administration involved with the scheme. It’s beneficial to have a mortgage professional by your side.
A shared ownership mortgage broker can help you compare deals and recommend the best one for your personal situation.
Shared ownership isn’t suitable for everyone, and your mortgage advisor will help you understand its advantages and disadvantages.
We believe shared ownership can be a fantastic option for the right individuals. It provides both first-time buyers and home movers the opportunity to purchase a property without needing a large deposit.
Saving for a deposit can be difficult and time-consuming, especially if you are renting or paying a mortgage.
With shared ownership, the deposit required is a minimum of 5% of the share you are purchasing, not the full market price. For example, if you were buying a 50% share of a property worth £200,000, you would need a minimum deposit of £5,000. Without the scheme, you would need £10,000.
However, if you can afford to buy a property that meets your family’s needs without the scheme, you would not be eligible for shared ownership.
Yes, if you can afford it, you have the option to ‘staircase’ and purchase a larger share of your property in the future. Your landlord will set terms and conditions regarding how much and when you can buy additional shares.
To finance the purchase of the additional share, you can use a further advance mortgage from your existing lender, remortgage if you are no longer tied to a deal, or take out a secured loan.
Yes, with a shared ownership property, you’ll pay rent and service charges to the landlord for the portion of the property that you do not own.
The rent payable will need to be considered when calculating your mortgage affordability. You and the landlord will agree on the rent amount, payment schedule, service charge, and what it covers.
If you eventually own 100% of the property, you will no longer pay rent to the landlord. However, as shared ownership properties are leasehold, a service charge will still be payable.
Getting a mortgage with shared ownership is a process similar to a standard application, though the rent and any service charges or ground rent you’ll pay will be factored in. With a good shared ownership mortgage broker on your side, these mortgages are not considered overly difficult to obtain.
To secure a shared ownership mortgage, we’ll need to consider:
– Your income, including its stability, amount, and regularity. – Existing credit commitments, such as personal loans, car loans, credit cards, etc. – Account conduct, as your credit score will be assessed. – Affordability, including how much spare income you have left each month. – Your dependents, such as children, who rely on your income. – The amount of deposit you can put down, as a larger deposit can lower your mortgage payments.
Shared ownership mortgages can be complex, so having a specialist mortgage broker by your side can prove invaluable.
No, you’ll need to put down a 5% deposit for a shared ownership mortgage, but it’s 5% of the share you purchase.
100% mortgages for shared ownership properties are unavailable; the highest loan-to-value (LTV) ratio on the market is a 95% shared ownership mortgage.
The deposit for a shared ownership mortgage is smaller than that for a regular mortgage because it is based on the share you are buying, not the full market value of the property.
Whether shared ownership is better than renting depends on your situation; it’s not suitable for everyone.
If you are currently renting, the advantages of shared ownership include:
– You’ll only need a 5% deposit calculated on the share you are buying. – The scheme can help you afford a larger property. – Rent can feel like ‘dead money’, whereas, with shared ownership, you benefit from any increases in the property’s value on your share.
For renters, the disadvantages can be:
– You’ll be responsible for the maintenance and upkeep of the property. – You’ll still need to pay rent on the share of the property you do not own. – There will be ground rent and service charges to pay. – Shared ownership properties can be harder to sell. – The interest rate on your mortgage may be slightly higher than a regular mortgage.
Several banks and lenders in the UK offer shared ownership mortgages. Here are just some of the major ones:
- Barclays
- HSBC
- Nationwide Building Society
- Halifax
- Lloyds Bank
- NatWest
- Santander
- Yorkshire Building Society
- Leeds Building Society
- TSB
These banks provide various shared ownership mortgage products. It’s advisable to consult with a mortgage broker who specialises in shared ownership to find the best deals tailored to your specific situation.
There isn’t a minimum income requirement for shared ownership. However, you must pass your lender’s affordability assessments if you need a mortgage.
A maximum household income limit to qualify for the scheme varies depending on your location.
The downside to shared ownership is that it can be costly on a monthly basis, as you must account for your mortgage payment, ground rent, service charge, and rent in addition to other expenses such as life insurance, home insurance, energy bills, and council tax.
If you choose to purchase a larger share in the future, the rent you pay will decrease.